

Are Non-Executive Directors Personally Liable for Debts?
It is one of the first questions a prospective non-executive director asks, and one that many only ask once a company is already in trouble: if the business runs up debts it cannot pay, could I end up paying them? The reassuring answer is that, in the ordinary course, you will not. The important qualification is that the law lifts that protection in specific circumstances, and in an insolvency those are exactly the circumstances an insolvency practitioner will examine.
This article is about personal liability for the company’s debts. It does not try to cover every duty a director owes. For the full picture of what the law expects of you, read our guide to the legal duties of a non-executive director in the UK, and for how those duties play out in practice, see NED responsibilities and legal duties. This article is general information, not legal advice; if you are concerned about a specific company, take advice from a solicitor or licensed insolvency practitioner.
The General Rule: The Company’s Debts Are the Company’s
A limited company is a separate legal person. It owns its assets, it enters its own contracts and it owes its own debts. Shareholders’ liability is limited to what they paid, or agreed to pay, for their shares, and directors are not, simply by holding office, guarantors of what the company owes. If the company cannot pay its suppliers, lenders or landlord, the starting point is that those creditors’ claims are against the company, not against the people on its board.
That rule holds for the great majority of non-executive directors for the whole of their time on a board. It is what makes it possible for experienced people to serve on boards at all. The exceptions below do not undermine it. They are specific situations in which the law holds a director personally responsible because of something the director agreed to, did, or failed to do.
Two points are worth making at the outset. First, the label “non-executive” gives no special protection. Company law recognises one kind of director, and the duties in the Companies Act 2006 apply to every director equally. Our article on directors’ duties under the Companies Act 2006 explains them. Second, most of the exceptions turn on conduct. A NED who engages properly, asks the right questions and acts when the warning signs appear is in a very different position from one who did not.
Exception 1: Personal Guarantees
The simplest way to become liable for a company’s debt is to agree to it. Banks, asset finance providers, landlords and some suppliers ask directors to guarantee the company’s obligations, particularly in smaller and younger businesses. A personal guarantee is a contract between you and the creditor. If the company defaults, the creditor can pursue you directly, and limited liability does not help, because you have chosen to step outside it.
Non-executive directors are asked to give guarantees less often than founders and executive directors, but it does happen, especially in owner-managed businesses where the lender wants every director committed. Our firm view is that a NED should be extremely cautious about giving one. It compromises independence, because you now have a personal financial stake in the company’s borrowing decisions, and it can expose you to losses out of all proportion to your fee. If a guarantee is requested, it belongs in the conversation about your terms before you accept the role. Our guide to negotiating board role terms covers the questions to ask.
Exception 2: Wrongful Trading
Wrongful trading is the exception that matters most to non-executives. Under section 214 of the Insolvency Act 1986, if a company goes into insolvent liquidation or administration, the court can order a director to contribute to the company’s assets if, at some point before then, the director knew or ought to have concluded that there was no reasonable prospect of avoiding insolvent liquidation or administration, and did not then take every step they ought to have taken to minimise the potential loss to creditors.
Three features make this important for NEDs:
- It is judged on what you ought to have known. The test looks at the knowledge, skill and experience reasonably expected of a person carrying out your functions, and at the knowledge, skill and experience you actually have. A chartered accountant chairing the audit committee will be held to a higher standard on the financial position than a NED appointed for sector expertise.
- Not attending is not a defence. A director who did not read the papers, did not ask about cash or missed the meetings where the position was discussed is not protected by their own absence.
- The defence is to act. A director who recognised the position and then took every step to minimise loss to creditors, such as taking advice, pressing for an insolvency professional to be consulted and stopping the company from running up new credit it cannot pay, has the statutory defence.
In practice, the best protection is oversight of cash before a crisis arrives. That means a credible cash flow forecast, covenant tests and a board that discusses them. Our guide to board oversight of cash flow forecasting sets out what NEDs should see and ask for, and our article on the NED’s role when a company faces insolvency covers the period when the position has turned.
Exception 3: Fraudulent Trading
Section 213 of the Insolvency Act 1986 allows the court, in a winding up, to order anyone who was knowingly a party to carrying on the company’s business with intent to defraud creditors, or for any fraudulent purpose, to contribute to the company’s assets. Fraudulent trading is also a criminal offence under the Companies Act 2006.
The key word is “knowingly”. This is about dishonesty, not misjudgement, and an honest NED who misread a difficult situation is dealing with wrongful trading rather than fraudulent trading. The relevance for non-executives is that turning a blind eye can be treated as knowledge. If you suspect that the company is taking on credit it has no intention of repaying, or that creditors are being misled, the answer is to raise it formally at the board and take advice, not to keep quiet.
Exception 4: Misfeasance and Breach of Duty
Under section 212 of the Insolvency Act 1986, a liquidator, creditor or contributory can apply to the court where a director has misapplied or retained company money or property, or has been guilty of misfeasance or breach of any fiduciary or other duty. The court can order the director to repay, restore or contribute compensation.
Misfeasance claims are how a liquidator pursues breaches of the general duties after a company has failed: approving transactions that benefited insiders at the company’s expense, allowing unlawful dividends, or failing to consider creditors’ interests when the company was in financial difficulty. That last point matters. When a company is insolvent or close to it, directors must have proper regard to the interests of creditors, and decisions that ignore them can later be challenged. Board minutes that show the creditor position was considered are an important protection.
Exception 5: HMRC Personal Liability Notices for National Insurance
Unpaid National Insurance contributions are one of the few areas where tax debts can follow a director personally outside insolvency proceedings. Under section 121C of the Social Security Administration Act 1992, where a company fails to pay National Insurance contributions and the failure appears to HMRC to be attributable to fraud or neglect on the part of one or more of its officers, HMRC can serve a personal liability notice on those officers, making them personally liable for the amount.
“Neglect” is the important word for non-executives. A NED is not expected to run payroll, but a board that knew PAYE and National Insurance were being left unpaid to fund trading, and did nothing, is exposed. Watching the arrears position with HMRC, and asking about time-to-pay arrangements, is part of a NED’s financial oversight. Our article on whether non-executive directors pay National Insurance covers the separate question of how NED fees themselves are taxed.
Exception 6: Joint and Several Liability Notices
Part 4 of the Finance Act 2020 gave HMRC a wider power to make individuals jointly and severally liable for a company’s tax liabilities in certain circumstances connected with insolvency. The power is aimed at tax avoidance, tax evasion and repeated insolvency, sometimes described as phoenixism, where a business deliberately leaves tax unpaid in one company and carries on in another.
These notices are targeted at people involved in abusive behaviour and are unlikely to touch a properly engaged NED on a well-run board. They are worth knowing about because they show how far the protection of limited liability can be set aside where tax is deliberately left unpaid, and why a non-executive should not be associated with a business that has a pattern of failed predecessor companies.
Exception 7: Disqualification and Compensation Orders
Disqualification is not a liability for the company’s debts in itself, but it can lead to one. The Insolvency Service investigates the conduct of directors of failed companies, and a director found unfit can be disqualified from acting as a director for between two and fifteen years under the Company Directors Disqualification Act 1986.
Since amendments made in 2015, the court can also make a compensation order against a disqualified director under section 15A of that Act, or accept a compensation undertaking. This requires the director to pay an amount for the benefit of creditors who lost out because of the conduct that led to the disqualification. A non-executive who failed to oversee obvious misconduct can be among the directors whose conduct is examined.
Exception 8: Reusing a Failed Company’s Name
Under section 216 of the Insolvency Act 1986, a person who was a director in the twelve months before a company went into insolvent liquidation must not, for five years, be a director of or involved with another company using the same name or a name so similar as to suggest an association, except with the court’s permission or within limited statutory exceptions. Breaching the rule is a criminal offence, and under the following section a person who acts in breach can be personally liable for the debts of the new company.
For a NED, this mostly matters after a failure, if a buyer of the business wants to retain the board or the brand. Taking advice before agreeing to serve on the new company is essential.
Warning Signs a NED Should Act On
| Warning sign | What to do |
|---|---|
| Cash forecasts show headroom falling month after month | Ask for a 13-week cash forecast and review it at every meeting |
| HMRC, pension or supplier payments are being delayed | Ask why, and whether time-to-pay arrangements are in place |
| A covenant breach is forecast | Ask what the lender has been told and what the plan is |
| The board is told the problem is temporary | Ask for evidence, and for the downside case |
| Directors disagree about whether the company can pay its debts | Take independent insolvency advice, and record it in the minutes |
Once there is a real risk of insolvency, directors must give weight to the interests of creditors. Acting early, taking advice and recording the board’s reasoning are the best protections.
Adrian says
Watch the cash, not just the profit
As a former Finance Director, I have seen how a business can report a profit while running short of cash. The warning signs show up first in the cash forecast and in which suppliers are being paid late.
A NED who asks to see the cash forecast at every meeting, and asks what has changed, is far better placed than one who only reads the profit and loss account.
Adrian Lawrence FCA, Founder, NED Capital
How Non-Executive Directors Protect Themselves
The protections are well established, and most of them are within a NED’s own control.
- Do your due diligence before you join. Read the last two sets of accounts, the most recent management accounts and the cash forecast, and ask about banking covenants, arrears with HMRC and any guarantees requested. Our guide on when a NED should walk away from a board appointment sets out the red flags.
- Insist on D&O insurance and a deed of indemnity. Directors’ and officers’ insurance can meet defence costs and some claims, and the Companies Act allows a company to buy it for its directors. It will not cover everything, and it will not pay a personal guarantee, but it matters. Our article on what insurance non-executive directors need explains what to check.
- Read the papers and ask about cash. The wrongful trading test looks at what a reasonable director in your position would have known. Asking about cash, covenants and creditor pressure at every meeting is the single best protection.
- Make sure your challenge is minuted. If you raise a concern, check the minutes record it. Our guide to what a board meeting is covers how minutes work and why they matter.
- Take advice early. When the position is deteriorating, press for the board to take advice from an insolvency professional. Doing so is one of the clearest ways to show you were acting to protect creditors.
- Resign carefully, not reflexively. Resigning when a company is in difficulty can look like walking away rather than minimising loss. Take advice first, and set out your reasons in writing. Our guide on knowing when it is time to step down covers how to leave well.
For a broader, candid view of what the role involves, our article on time commitment, liabilities and pay is a good companion to this one. If you are joining a business that is already in difficulty, our page on turnaround and restructuring NEDs explains what boards in that position look for.
Frequently Asked Questions
Is a non-executive director personally liable if the company goes bust?
Not automatically. A limited company’s debts are its own. A NED becomes personally exposed only in specific circumstances, such as having given a personal guarantee, wrongful or fraudulent trading, misfeasance, or an HMRC personal liability notice. Most NEDs on properly run boards never face any of these.
Does being non-executive reduce my liability for wrongful trading?
No. The wrongful trading test applies to every director. It takes account of the functions you carry out and your own knowledge and experience, so a NED with financial expertise can be held to a higher standard on financial matters than one without.
Will D&O insurance cover me if I am personally liable for the company’s debts?
Partly, at most. D&O insurance can meet defence costs and some claims arising from your conduct as a director, but policies have exclusions and limits, and they do not cover personal guarantees. Read the policy and the indemnity before you join.
Can HMRC make a NED pay the company’s unpaid tax?
In specific circumstances. HMRC can serve a personal liability notice for unpaid National Insurance where the failure is attributable to an officer’s fraud or neglect, and can issue joint and several liability notices in certain cases involving tax avoidance, evasion or repeated insolvency.
Should I resign if I think the company is insolvent?
Not without advice. Resigning does not end your exposure for what happened while you were in office, and the wrongful trading defence depends on taking every step to minimise loss to creditors. Raise your concerns formally, make sure they are minuted, and take legal advice before deciding.
Should a NED ever give a personal guarantee?
Rarely, and only with independent legal advice. A guarantee creates direct personal liability and compromises your independence. If one is required as a condition of the role, treat it as a central part of the decision to accept.
Related Guides and Services
Understanding and managing a director’s exposure.
Duties
What the Law Expects
→ Legal Duties of a NED
→ Companies Act Duties
→ Why Regulators Target NEDs
Protection
Before and During the Role
→ Insurance for NEDs
→ Negotiating Board Terms
→ When to Walk Away
Financial Distress
When Things Turn
→ The NED’s Role in Insolvency
→ Cash Flow Oversight
→ Turnaround NEDs
Adrian Lawrence FCA — Founder, NED Capital
Fellow of the ICAEW | Chartered Accountant holding an ICAEW practising certificate | Sister practice of FD Capital
Adrian holds a BSc from Queen Mary College, University of London and is a former listed-company Finance Director with more than 25 years at C-suite level, working with boards, investors and business owners across the UK. He founded NED Capital to connect organisations with the independent non-executive directors they need, and oversees the senior search team that runs every board mandate we accept.
Considering a Board Role?
Call 0203 137 2496 or email recruitment@nedcapital.co.uk to talk confidentially about a non-executive appointment, or register as a NED candidate. NED Capital is part of FD Capital Group, five specialist recruitment firms, with offices at 167–169 Great Portland Street, London W1W 5PF and Watling Court, Orbital Plaza, Cannock WS11 0EL.
NED Capital | Part of FD Capital Group | Founded by Adrian Lawrence FCA, ICAEW practising certificate holder
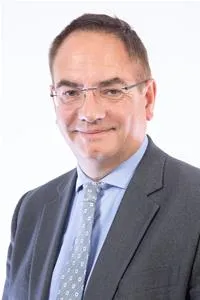
Adrian Lawrence FCA is the founder of NED Capital and a Fellow of the Institute of Chartered Accountants in England and Wales (ICAEW) and holds an ICAEW practising certificate in his own name. He holds a BSc from Queen Mary College, University of London, and has more than 25 years at C-suite level, working with boards, investors and business owners across the UK. He founded NED Capital to connect businesses with the independent Non-Executive Directors they need to provide challenge, governance and strategic oversight — and personally leads candidate assessments for board-level appointments.


 Accredited member of GBC.
 Carbon offset via Tree Nation